Are you a VAT registered business looking to figure how VAT is applicable on your food items? Read on to find out more about applicable rates of VAT on food items.
Zero-rated VAT on food items
- – Raw meats and fish
- – Vegetables and fruit
- – Cereals, nuts, and pulses
- – Culinary herbs
Whether you supply these unprocessed foodstuffs direct to the public or for use as ingredients in the manufacture of processed food, they must be fit for human consumption.
Here’s a useful summary for VAT on food items:
| Food Item | Rate of VAT | Notes |
| Meat and poultry, for example | Zero rate | Butchered or complete carcass |
| beef, lamb, pork, chicken etc. | ||
| Exotic meat, for example, | Zero rate | Butchered or complete carcass |
| horse, ostrich, crocodile, | ||
| kangaroo, and so on | ||
| Fish | Zero rate | If fit for human consumption |
| Vegetables and fruit | Zero rate | If of a quality fit for human consumption |
| Culinary herbs and spices | Zero rate | See VAT Notice 701/38: seeds and plants |
| Ornamental vegetables | Standard Rate | For example, cabbages, that are |
| grown for their appearance | ||
| rather than consumption | ||
| Juice and juice concentrates | Standard Rate | see paragraph 2.2 |
| Nuts and pulses | Zero rate | If raw and unprocessed for |
| human consumption |
VAT on home cooking and baking items
You can use zero rates for products sold for use as an ingredient in home cooking or baking:
| Food Item | Rate of VAT | Notes |
| Prepared cake, sauce, soup, and other mixes | Zero rate | For use as an ingredient in the home kitchen |
| Mixes for ice cream and similar frozen products | Standard rate | See paragraph 3.5 |
| Sweeteners | Zero rate | Including natural products like honey and sugar, |
| and artificial products like saccharin |
VAT on food supplied in the course of catering
You must always standard rate food supplied in the course of catering (subject to the rules on the temporary 5% reduced rate of VAT that will apply between 15 July 2020 and 31 March 2021) including hot take-away food.
Further information can be found in VAT Notice 709/1: catering and take-away food.
VAT on food not supplied in the course of catering
Most food of a kind used for human consumption (see paragraph 2.3) is zero-rated. There are, however, some exceptions as follows:
| You must always standard rate | But you can zero rate |
|---|---|
| Ice cream, similar products, and mixes for making them – see paragraph 3.5 | Frozen yoghurt that’s designed to be thawed before being eaten |
| Confectionery, apart from cakes and some biscuits – see paragraph 3.6 | Drained cherries and candied peel |
| Alcoholic beverages – see paragraph 3.7 | – |
| Other beverages, and preparations for making them – see paragraph 3.7 | Milk and milk drinks, tea, maté, herbal tea, coffee and cocoa, preparations of yeast, meat and egg |
| Potato crisps, roasted or salted nuts and some other savoury snack products – see paragraph 3.8 | – |
| Products for home brewing and winemaking see paragraph 3.7 | – |
How these criteria apply to general and specialised food products is explained in section 3 and section 4.
VAT on biscuits
Biscuits covered or partly covered in chocolate or some other products similar in taste and appearance to chocolate are standard rated.
Examples to help determine whether a product is zero or standard-rated:
| Zero-rated | Standard rated |
|---|---|
| Chocolate chip biscuits where the chips are either included in the dough or pressed into the surface before baking | All wholly or partly coated biscuits including biscuits decorated in a pattern with chocolate or some similar product |
| Bourbon and other biscuits where the chocolate or similar product forms a sandwich layer between 2 biscuit halves and is not continued onto the outer surface | Chocolate covered shortbread |
| Jaffa cakes | Gingerbread men decorated with chocolate unless this amounts to no more than a couple of dots for eyes |
| Biscuits coated with caramel or some other product that do not resemble chocolate in taste and appearance | Ice cream wafers partly covered in chocolate such as ‘chocolate oysters’ |
VAT on hot food
Many bakery products, particularly bread, pies, pasties and other savouries, are baked on the retail premises and are sold whilst still hot. The borderline between ‘freshly baked’ and ‘hot take-away’ food can be a difficult one, and if you sell any hot food you’re advised to read VAT Notice 709/1: catering and take-away food which sets out the distinction in more detail. If you’re still in any doubt contact the VAT: general enquiries helpline.
VAT on confectionery
Standard-rated confectionery includes chocolates, sweets and candies, chocolate biscuits and any other ‘items of sweetened prepared food which is normally eaten with the fingers. Items of sweetened prepared food do not need to have added sweetening if they are inherently sweet, for example, certain fruit and cereal bar products.
Here are some examples of the standard and zero-rated confectionery:
| Zero-rated VAT on Food Items | Standard rated VAT on Food Items |
|---|---|
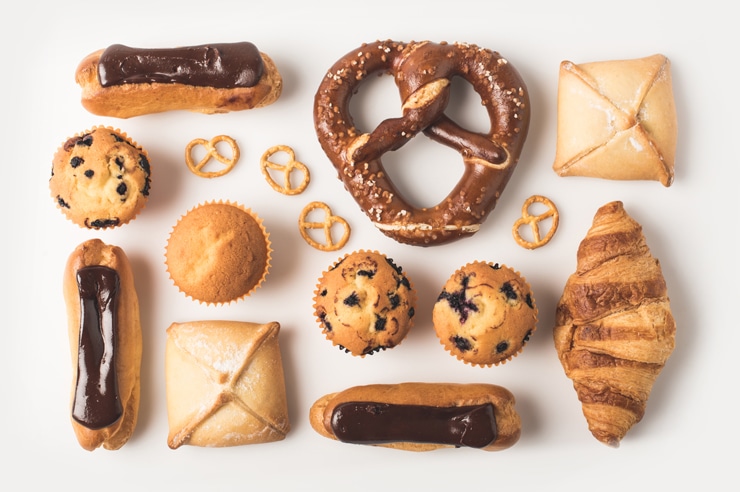
| Cakes including sponge cakes, pastries, eclairs, meringues, flapjacks, lebkuchen, marshmallow teacakes and Scottish snowballs | Chocolates, bars of chocolate including those containing nuts, fruit, toffee, or any other ingredients, diabetic chocolate, liqueur chocolates and similar sweets |
| Chocolate spread, liquid chocolate icing, chocolate couverture, and chocolate chips, strands, vermicelli, mini-buttons etc held out for sale solely for culinary use; chocolate body paint | Sweets, pastilles, gums, lollipops, candy floss, sherbet, chewing gum, bubble gum, Turkish delight, marshmallow, fondants and similar confectionery |
| Biscuits coated with icing, caramel or some other product different in taste and appearance from chocolate | Compressed fruit bars and other items of prepared dried fruit confectionery that are sweet to the taste |
| Chocolate cups | Sweetened popcorn |
| Toffee apples and other apples on a stick covered in chocolate, nuts and so on | Nuts or fruit with a coating, for example of chocolate, yoghurt or sugar |
| Ginger preserved in syrup drained ginger or dusted ginger can be zero-rated as long as it’s not held out for sale as confectionery | Crystallised, sugared or chocolate-covered ginger |
| Candied peels, angelica, drained cherries for use in home baking often described as ‘glacé’ cherries and cocktail or maraschino cherries | Drained, glacé or crystallised fruits including Petha, Marrons glacés |
| Halva (unless coated with chocolate or chocolate substitute or held out for sale as confectionery) | Bars consisting mainly of seeds and sugar or other sweetening matter |
| Edible cake decorations | Cereal bars, whether or not coated with chocolate, with the exception of bars that qualify as cakes |
| Sweet tasting dried fruit held out for sale as snacking and home baking | Sweet tasting dried fruit held out for sale as confectionery, snacking |
| Traditional Indian and Pakistani delicacies such as barfis, halvas, jelabi, laddoos; and traditional Japanese delicacies | Slimmers’ meal replacements in biscuit form that are wholly or partly covered in chocolate or something similar in taste and appearance |
Need help with VAT on Food Items?
Contact MCL Accountants Southend on 01702 593 029 to optimise your tax position or if you need any assistance with your VAT returns if you are unsure about VAT on Food items.
- ABOUT
- REQUEST A QUOTE

Ishan provides financial management, taxation and transactional advice to business entities of all sizes. His expert areas include statutory compliance, business taxation, personal tax & transactional processing and systems. Industry sectors include professional services, retail, hospitality and entertaining & media and advertising services.